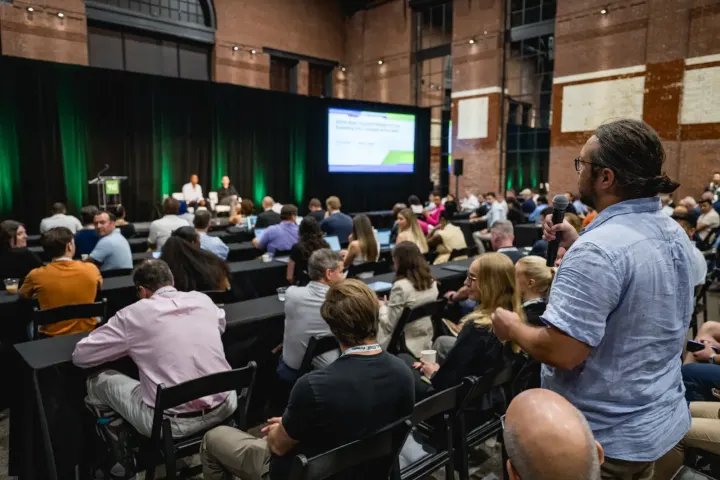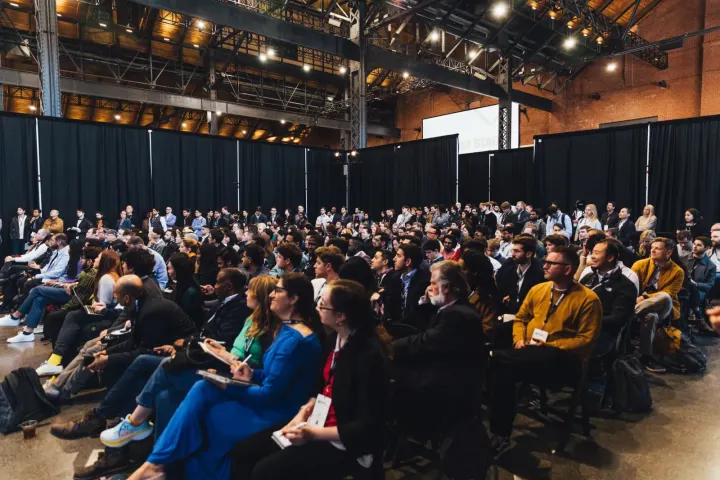
Pakistan fintech is at a fork in the road, facing a choice between continuing to adopt tools built abroad or developing native technologies. Minister of State and Pakistan Virtual Assets Regulatory Authority Chairman Bilal Bin Saqib delivered this stark warning on 2 November 2026 in Lahore. Speaking at the PBA, LUMS Dialogue on Digital Assets and the Future of Banking, he stressed that the nation must stop relying entirely on foreign financial infrastructure.
The stakes are high for local startups, established banking institutions, and millions of consumers who navigate the country's digital economy daily. Economists and technology specialists note that financial sovereignty relies heavily on who designs the core plumbing of modern transactions. When nations only consume foreign applications, they surrender control over fees, regulatory compliance, and cross-border capital flows.
Pakistan Fintech Cannot Afford to Stay a Consumer
During his address in Lahore, Bilal Bin Saqib said Pakistan must move from being a consumer of global financial technologies to becoming an active contributor. He explained that this transition is necessary to shape the infrastructure, standards, and innovation defining tomorrow's financial markets.
The warning carried real weight because it stems from recent history. Recalling the country's limited participation in the development of international correspondent banking and card payment systems, he noted that Pakistan continued to bear the costs of that exclusion. When global powers designed the plumbing of modern money decades ago, local financial institutions were not in the room. Pakistani businesses and consumers have been paying extra ever since through higher transaction fees, slower cross-border payments, and restricted access to global capital markets.
His message was direct and aimed squarely at the current generation of entrepreneurs. The core question is whether the country wants to rent its financial future or own it. That framing determines how startup founders and bank executives allocate capital, hire engineering talent, and plan product roadmaps.
What Building Actually Looks Like for Pakistan Fintech
Building domestic capabilities does not require reinvention from scratch, according to the PVARA chairman. Technological independence does not demand that local engineers replicate every international network. Instead, the focus should rest on specific high-impact sectors where local teams can move rapidly to establish market dominance.
Artificial intelligence formed a central pillar of this argument. Modern AI tooling allows compact development teams to build products that previously required massive engineering departments. This evolution effectively removes historical barriers to entry for emerging markets.
The convergence of artificial intelligence and blockchain technology opens doors for highly automated and agentic business models. Individual entrepreneurs can now launch enterprises with operational capacities once restricted to large corporations. Given the nation's young, tech-savvy population and lower operating expenditures, this dynamic creates a powerful structural advantage.
Addressing students and young professionals, he encouraged them to create globally competitive financial technologies. He expressed confidence that the country possesses the necessary human capital to emerge as a regional powerhouse for digital finance.
The Role of Regulators and Banks in Shaping Markets
The call to action extends far beyond startup founders, placing heavy responsibilities on traditional banking institutions. Commercial lenders must upgrade their technological infrastructure, invest in artificial intelligence, train existing staff, and deepen partnerships with academic institutions like LUMS.
Regulatory bodies must simultaneously harmonize their approaches. Saqib emphasized that PVARA, the State Bank of Pakistan, and other authorities need to coordinate mandates effectively. This cooperation ensures robust cybersecurity, consumer protection, and financial stability without stifling commercial ingenuity.
Regulatory alignment represents a major shift from past practices where agencies operated in isolation. The introduction of the PVARA regulatory sandbox offers a controlled legal environment for blockchain and virtual asset ventures. Startups can test novel products under official supervision, escaping the legal ambiguities that historically choked investment and delayed commercial scaling.
Why the Numbers Back Up the Ambition
Quantitative metrics validate these ambitious goals across the domestic startup landscape. Approximately 450 fintech enterprises operating across the country have collectively secured roughly $391 million in venture capital funding. The broader entrepreneurial ecosystem has achieved a combined enterprise value exceeding $4 billion, surging 3.6 times since 2020.
Consumer adoption rates provide an equally solid foundation for domestic builders. Chainalysis ranks the nation third globally in crypto adoption, trailing only India and the United States. This organic demand demonstrates that everyday citizens are eager to embrace digital financial tools.
The primary missing element is not consumer demand, but rather domestic supply. Local founders must create indigenous products, train native engineers, and scale companies capable of exporting solutions abroad. Solving localized challenges like high remittance costs, agricultural financing, and informal-economy payments will build a template that other emerging markets can adopt.