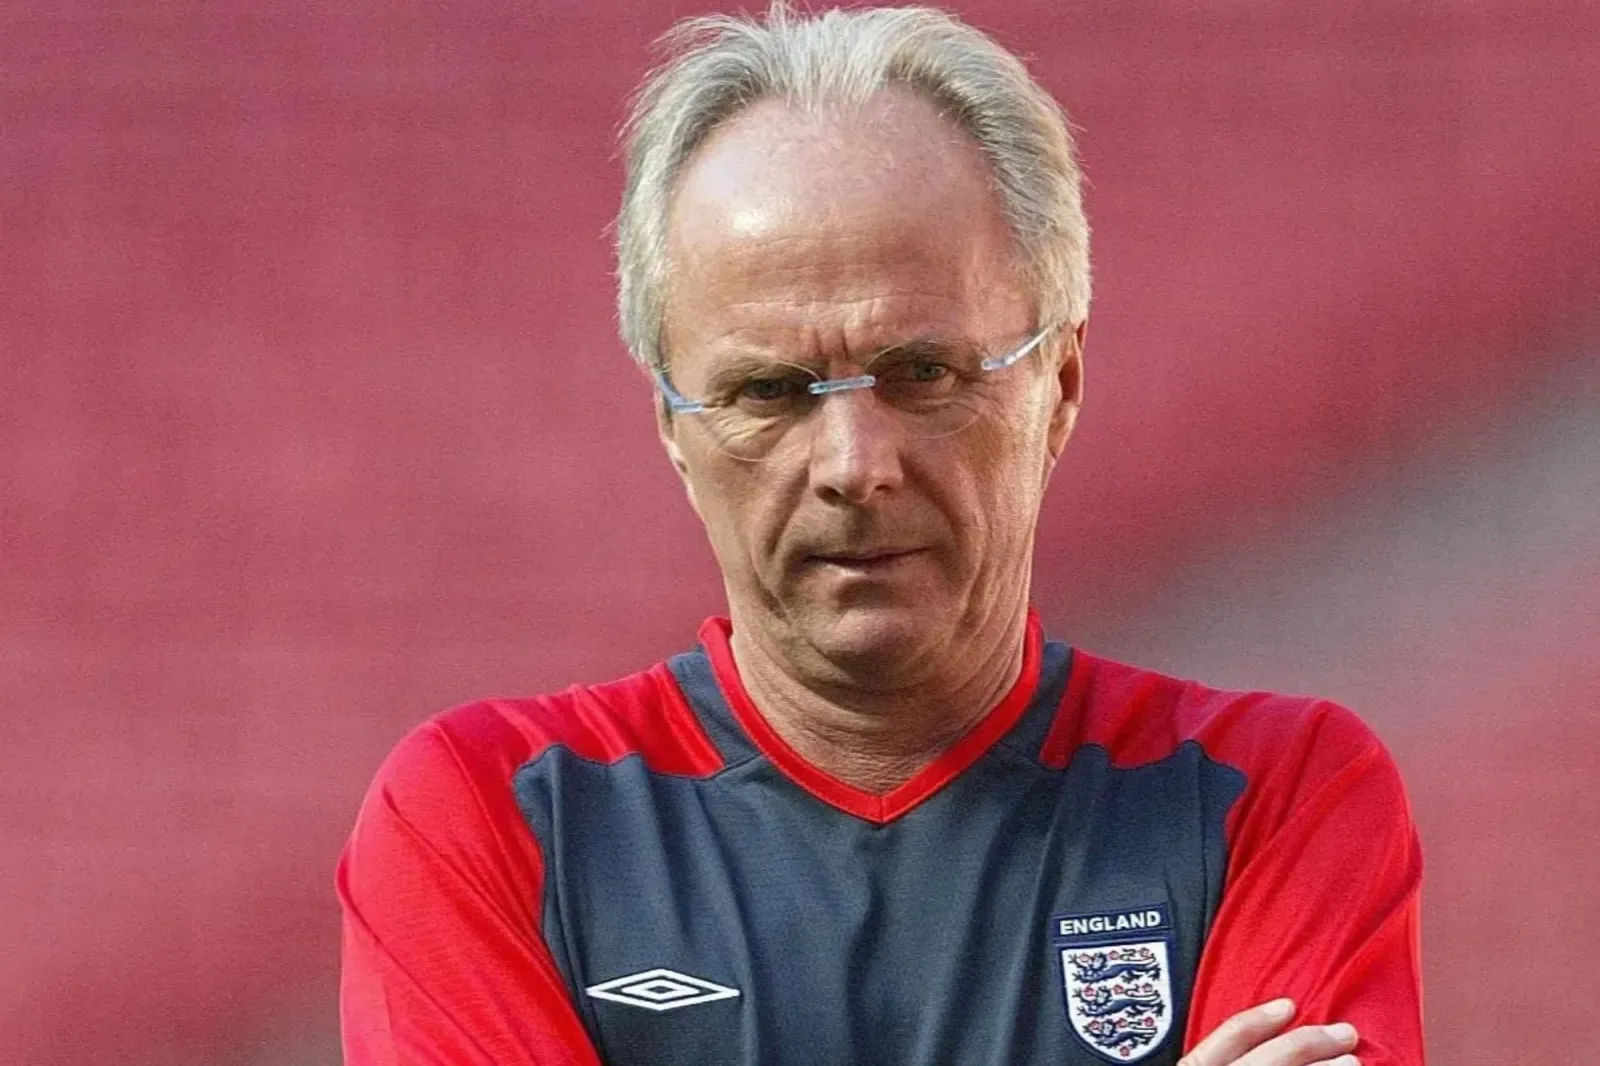
HMRC officials have demanded £3.5 million in unpaid tax from the estate of former England football manager Sven-Göran Eriksson, who died of pancreatic cancer in August 2024 at age 76.
The tax authority's claim comes as Eriksson's lawyer, Anders Runebjer, told The Sun that the only assets he can locate are roughly £1 million held in a Cayman Islands account and £300 000 in a UK bank, leaving no further funds to satisfy the demand.
Why HMRC Is Seeking the Debt
HMRC says the sum represents tax that was due for the period after Eriksson left the England job in 2006, plus interest accrued up to his death. The agency's standard practice is to treat unpaid tax as a liability of the deceased's estate, meaning executors must settle the debt before any distribution to heirs.
In this case, the tax bill reportedly grew to £3.5 million after HMRC applied interest and penalties for late payment. The agency has not released a detailed breakdown, but the figure aligns with typical rates applied to high-income individuals whose tax returns are delayed or amended.
What the Lawyer Says About Available Funds
Anders Runebjer, representing Eriksson's children Johan (47) and Lina (39), said: "Sven earned millions but was always too busy with his football and his ladies to manage money very well." He added, "I told the HMRC I'm not able to get the money in the Cayman Islands or his UK bank and said they're welcome to seize it."
Runebjer continued, "They replied that they couldn't do that so I told them there was nothing else left, so they won't get paid." He emphasized that his priority is to locate any remaining inheritance for the children, not to satisfy the tax authority: "My priority is trying to get whatever money I can that he left for his children, not the British taxman."
According to Runebjer, the only identifiable assets are the £1 million offshore and the £300 000 domestic account. He claims HMRC has indicated it cannot directly seize the offshore funds, a position that may change if the agency pursues a legal route to access the Caribbean haven.
Background on Eriksson's Career and Earnings
Sven-Göran Eriksson, a Swedish manager, commanded a reported £25 million salary while leading the England national team from 2001 to 2006. His tenure, often referred to as the "Golden Generation" era, featured players such as David Beckham, Steven Gerrard, and Frank Lampard. Despite high expectations, England failed to win a major trophy under his guidance.
Beyond the England job, Eriksson managed clubs including Manchester City, Leicester City and Italy's Lazio, adding further to his earnings. His public profile was amplified by high-profile relationships, notably with former partner Nancy Dell'Olio, and reported affairs with TV personality Ulrika Jonsson and former FA secretary Faria Alam.
Understanding the Tax Implications of Death
When a UK taxpayer dies, any outstanding tax liabilities become the responsibility of the estate. Executors must file a final tax return covering the period up to the date of death and settle any balance before assets can be distributed. If the estate lacks sufficient liquid assets, HMRC may seek a court order to claim from overseas holdings, though this process can be lengthy and requires proof of ownership.
HMRC's interest in the Cayman Islands account reflects its broader policy of pursuing offshore assets linked to UK tax debts. The agency can issue a "distraint" order, but enforcement depends on cooperation from the jurisdiction where the funds are held. The Cayman Islands have a reputation for strict confidentiality, which can complicate recovery.
Potential Legal Paths for HMRC
The article notes that HMRC investigators are "weighed up a legal move to claw back their share from the Caribbean haven." In practice, this could involve:
- Applying for a UK court order that recognises the tax debt as a charge against the offshore account.
- Seeking mutual assistance under the UK-Cayman Islands tax information exchange agreement, which allows authorities to request information and, in some cases, freeze assets.
- Initiating civil proceedings in the Cayman courts, which would require establishing Eriksson's beneficial ownership of the account.
Each step incurs costs and may be contested by the estate's representatives, especially if they argue the funds are protected trusts or held in the name of a third party.
Impact on Eriksson's Children
Johan and Lina Eriksson stand to inherit any remaining assets after the tax claim is resolved. With only £1.3 million identified, the estate's net value could be significantly reduced once HMRC's £3.5 million demand, plus interest, is accounted for.
Runebjer's statements suggest the family is focusing on locating any hidden or undisclosed investments that could augment the inheritance. The outcome will depend on whether HMRC succeeds in accessing the offshore funds and whether any additional assets emerge during the probate process.
For the children, the immediate practical concern is cash flow for living expenses, education, and any business interests they may have. If HMRC's claim is upheld, they may receive little or nothing from the estate.
What Comes Next
HMRC has not commented publicly, stating only that it "cannot comment on individuals." The next procedural steps are likely to include:
- A formal notice of liability sent to the executors of the estate, outlining the amount owed and the deadline for payment.
- Potential court action by HMRC to obtain a charging order over the Cayman Islands account.
- Further investigation by the tax authority into any other assets, such as property, investments, or trusts that may have been omitted from the initial disclosure.
Observers will watch for any legal filings in UK courts, as well as any statements from the Cayman Islands financial regulator regarding cooperation with HMRC.
Practical Takeaways for Readers
For anyone with assets abroad, Eriksson's case underscores the importance of clear documentation and proactive tax planning. Failure to disclose offshore holdings can lead to significant liabilities for heirs.
Executors of estates should promptly engage tax specialists to assess any outstanding liabilities and to negotiate with HMRC where possible. Early settlement can reduce interest charges and avoid costly litigation.
Finally, individuals with high-income careers should maintain regular communication with tax advisors to ensure that any changes in tax law are reflected in their filings, minimizing the risk of large post-mortem claims.