Understanding the New FBR Tax Stamp Pricing for Cement Manufacturers
The Federal Board of Revenue has fixed the price of tax stamps for cement manufacturers at Rs1,140.64 per 1,000 Unique Identification Marks, commonly known as UIMs. This newly announced pricing structure incorporates an additional charge of Rs165.64 specifically designed to recover the annual maintenance costs associated with the digital monitoring apparatus. The Directorate General of Information Technology and Digital Transformation of the authority officially issued this notification on Thursday. Officials determined the updated price under Rule 150ZQH of Chapter XIV-B of the Sales Tax Rules, 2006, marking a notable update in how regulatory compliance is funded within the heavy manufacturing sector.
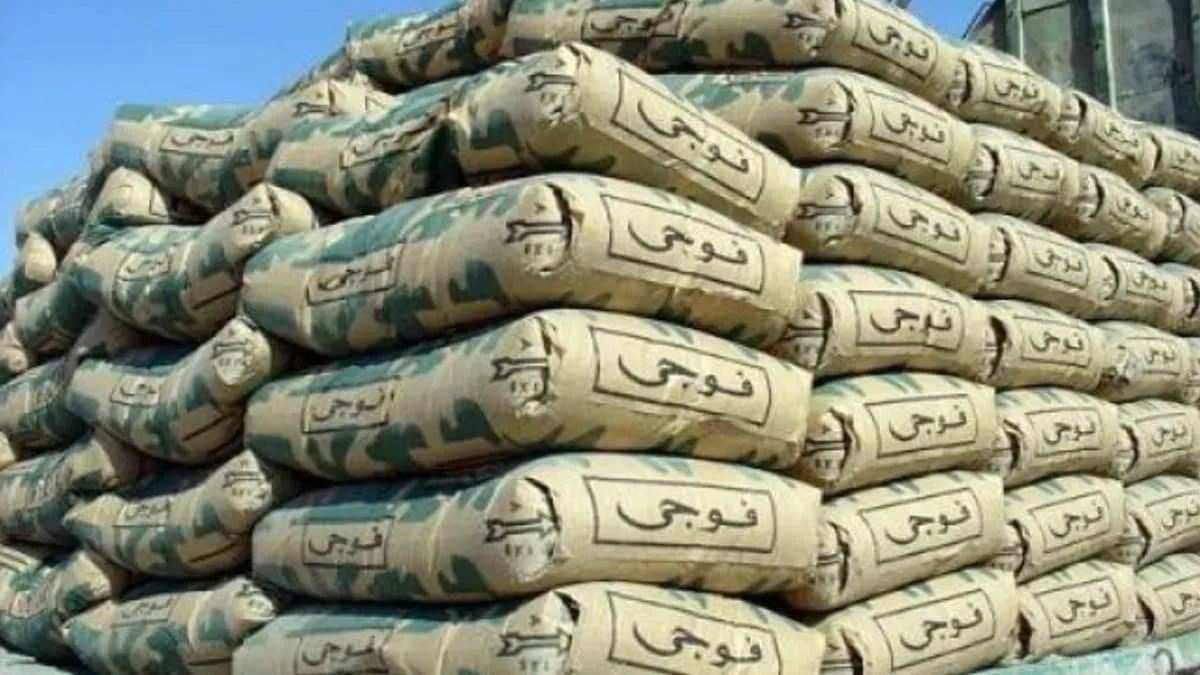
The implementation of this pricing adjustment directly impacts industrial operations across the country as companies adjust their financial planning to account for mandatory digital tracking expenses. Every bag of cement leaving production facilities requires proper marking to ensure tax compliance and prevent illicit trade within the construction materials market. By establishing clear financial parameters for these regulatory tools, the tax administration aims to maintain oversight of production volumes while transferring specific operational costs directly to the commercial entities involved in manufacturing.
Breakdown of the Base Rate and Additional Maintenance Charges
A closer examination of the pricing notification reveals how the final figure of Rs1,140.64 per 1,000 UIMs is calculated. The additional charge of Rs165.64 is levied on top of the established base rate of Rs975 per 1,000 UIMs. This surcharge covers specific maintenance service costs totaling Rs99,385,831 for the designated service year running from September 2026 to August 2027. Such financial allocations ensure the continuous technical support and operational integrity of the digital platform used for monitoring factory output.
The authority formulated these numbers following specific administrative steps and committee decisions. The formal notification traces its origin to the decision of the Licensing Committee made on April 30, 2025. Subsequent administrative actions, including letter F.No.2/Chairman LC/Price Review Petition/2025/4451 dated November 5, 2026, finalized the adjustments. Through these formal channels, the tax agency authorized its designated licensee to collect the prescribed price directly from cement manufacturers operating within the jurisdiction.
Timeline and Duration of the Updated Stamp Pricing
The newly established additional charge is subject to strict temporal and volume limits defined by the regulatory body. According to the official notification, the surcharge will remain in effect for a period of 12 months from the exact date of issuance. Alternatively, the collection of this increased rate will cease as soon as the licensee successfully sells 600 million UIMs to cement manufacturers, whichever condition occurs first. Once either of these thresholds is reached, the pricing structure will automatically revert to the base rate of Rs975 per 1,000 UIMs, unless tax authorities issue a new directive.
This conditional duration provides a clear framework for industrial planners who must budget for regulatory compliance over the coming months. Manufacturers must monitor their procurement volumes closely to anticipate when the pricing might shift back to the baseline figure. The oversight mechanism ensures that maintenance expenses are recovered transparently without imposing indefinite surcharges on the production sector.
Background of the Track and Trace System in Pakistan
The track and trace initiative was introduced by tax authorities to curb revenue leakage, document undocumented production, and combat counterfeiting in major sectors such as cement, sugar, fertilizer, and tobacco. By applying digital tax stamps containing Unique Identification Marks to packaging, the administration can track products from the factory floor to the final point of sale. This technological framework relies on specialized hardware and software managed by authorized private licensees under strict government supervision.
Over the years, the integration of digital monitoring has faced various administrative and financial reviews. Industry representatives and tax officials frequently engage in discussions regarding the operational costs associated with maintaining the system. Price review petitions, such as the one referenced in the recent notification, serve as the formal mechanism for adjusting service charges while balancing the financial responsibilities between the state, the technology vendor, and the manufacturing enterprises.
Impact on Cement Manufacturers and Market Dynamics
For industrial producers, the requirement to purchase Unique Identification Marks represents a recurring operational expense that directly affects the cost of goods sold. While large-scale cement producers possess the administrative infrastructure to absorb these compliance costs, smaller operators often face tighter profit margins. The addition of Rs165.64 for maintenance services increases the immediate capital required for procurement, especially for factories with high daily output volumes.
Beyond the direct financial outlay, compliance with the track and trace system demands strict adherence to operational protocols at production plants. Facilities must integrate the digital stamping equipment into their packaging lines without causing significant bottlenecks in production speed. Any technical failure in the scanning or application of UIMs can lead to temporary halts in manufacturing, making the reliability of the system crucial for business continuity.
What Watchers and Industry Observers Expect Next
Industry stakeholders will closely observe how the licensee manages the distribution of the 600 million UIMs tied to the current maintenance fee structure. Corporate financial planners will also prepare for the eventual expiration of the 12-month timeframe in late 2027, anticipating the potential return to the Rs975 base rate. Tax analysts expect the authority to continue evaluating the efficiency of the digital monitoring framework, ensuring that future adjustments align with actual maintenance expenditures and technological upgrades required by the sector.





