Zindigi Introduces Digital Overseas Accounts For Pakistanis Worldwide
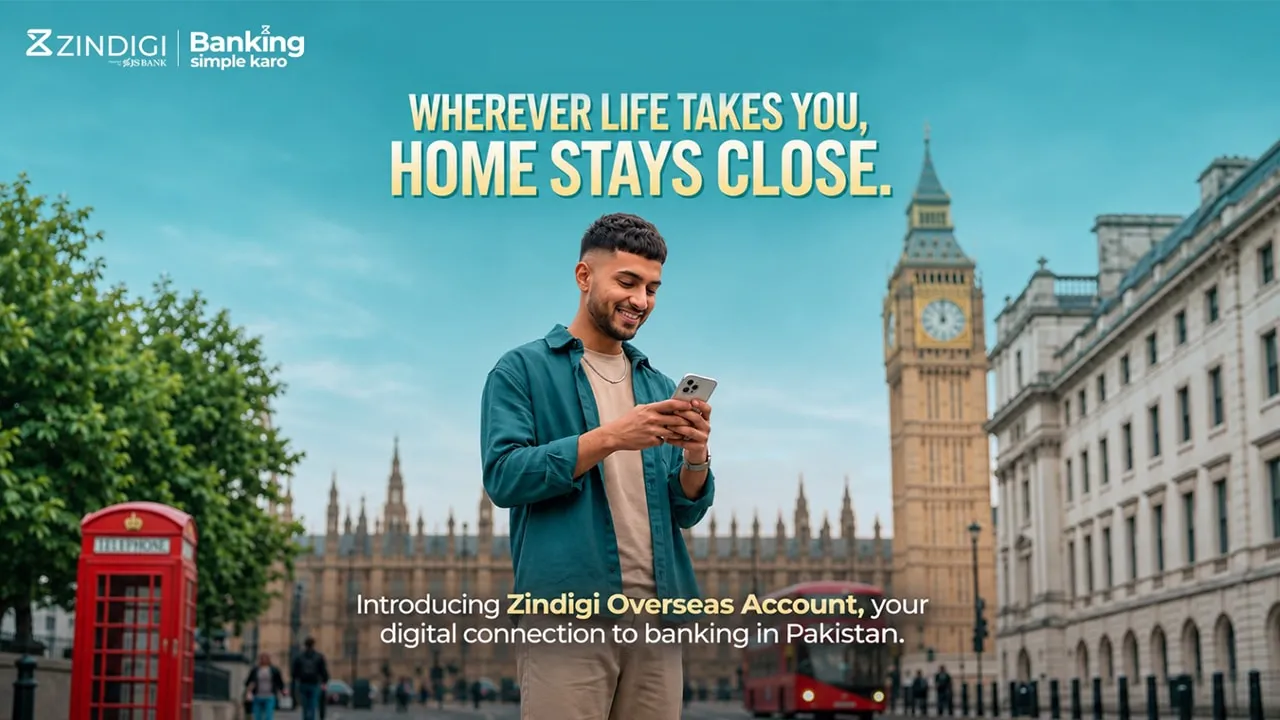
Zindigi, powered by JS Bank, has announced the launch of Zindigi Overseas Accounts, making it easier for Pakistanis living abroad to open and manage bank accounts in Pakistan, entirely digitally, without requiring a Pakistani mobile number or visiting a bank branch. The launch marks another milestone in the journey towards making banking simpler, more accessible, and borderless for Pakistanis worldwide. Millions of expatriates often struggle with legacy banking systems that demand physical verification or local phone numbers, creating friction when they try to support relatives or manage assets in their country of origin.
With Zindigi Overseas Accounts, eligible overseas Pakistanis can now register using their existing international WhatsApp numbers and open a fully digital bank account with an International Bank Account Number, rather than a conventional digital wallet. This technological integration bridges the gap between foreign residency and domestic financial management, allowing expatriates to retain full control over their funds through a smartphone application regardless of their physical location.
How Overseas Pakistanis Can Register Without a Local SIM
The traditional requirement of maintaining an active local mobile line has long frustrated diaspora communities wishing to execute everyday monetary tasks back home. By shifting verification protocols to international WhatsApp numbers, the platform removes a primary barrier to entry for non-resident citizens. Users no longer need to keep domestic SIM cards active while living abroad just to receive text message verification codes or banking alerts.
The digital onboarding facility is available to eligible holders of a Pakistan Origin Card, National Identity Card for Overseas Pakistanis, or Computerised National Identity Card. These official identity documents verify the user nationality and background, satisfying regulatory compliance standards while maintaining a completely paperless and remote application procedure through the mobile interface.
Features and Financial Services Available in the New Accounts
Designed around the everyday financial needs of overseas Pakistanis, the account enables customers to stay financially connected to home. From supporting family members and paying utility bills to managing household expenses and making local transfers, customers can conveniently manage their financial commitments in Pakistan through the Zindigi App, wherever they live. Expatriates frequently need to settle household liabilities, fund education expenses for relatives, or contribute to local investments without enduring the delays associated with wire transfers through traditional intermediaries.
Customers can choose between two account options, namely Non-Resident Account Repatriable and Non-Resident Account Non-Repatriable, depending on their financial needs and applicable regulatory requirements. Repatriable accounts typically allow funds to be sent back abroad with fewer restrictions, whereas non-resident non-repatriable accounts are tailored for domestic use and local investments within the borders of Pakistan. Understanding these financial classifications helps account holders select the proper framework for their long-term monetary strategies.
Leadership Perspective on Borderless Banking Innovation
Commenting on the launch, Noman Azhar, Co Founder & Chief Officer, Zindigi by JS Bank stated: At Zindigi, our vision is to make banking simpler, more accessible, and truly borderless for every Pakistani. The launch of Zindigi Overseas Accounts is another meaningful step towards that vision. We believe geographical boundaries should never limit access to financial services. By enabling overseas Pakistanis to open and manage their accounts digitally using their international mobile numbers, we are bringing banking closer to millions of Pakistanis who call another country home but remain deeply connected to Pakistan.
This initiative reinforces Zindigi's commitment to transforming banking through digital innovation, removing traditional barriers, and making essential financial services accessible to Pakistanis beyond geographical boundaries. Financial technology developers continue to target expatriate populations because remittances form a vital pillar of the national economy, driving foreign exchange inflows and household consumption across urban and rural districts alike.
Background on Expatriate Banking and Remittance Channels
Historically, non-resident citizens relied on basic foreign currency accounts or formal money transfer operators to send funds to their families. These legacy channels often involved steep fees, unfavourable exchange rates, and lengthy processing times that reduced the effective value of each transaction. Over recent years, regulatory bodies have introduced digital frameworks to encourage formal banking channels among the global diaspora, curbing informal hawala networks and increasing transparency.
Financial institutions operating within the country have progressively adopted smartphone applications to capture a larger share of diaspora remittances. By offering full International Bank Account Number capabilities instead of basic wallet limitations, providers give expatriates the same transactional power as domestic account holders. This includes direct utility payments, merchant settlements, and peer-to-peer transfers inside a unified application environment.
Impact of Digital Onboarding on the Pakistani Diaspora
The ability to establish domestic banking ties without visiting a physical branch benefits millions of workers and professionals residing in the Middle East, Europe, North America, and other global regions. Expatriates often face tight schedules and heavy work commitments in their host countries, making travel back to Pakistan exclusively for paperwork impractical. Remote verification via established identification cards and foreign mobile messaging applications eliminates travel costs and administrative delays.
Furthermore, local businesses and service providers stand to gain from smoother remittance flows and faster settlement of household expenses. Families dependent on financial support from abroad experience fewer disruptions when funds arrive instantly through digital channels rather than physical collection points. The transparency of digital ledgers also protects users from unexpected intermediary fees and security risks associated with physical cash handling.
Future Outlook for Borderless Financial Services
As regulatory authorities refine digital onboarding procedures, financial technology firms are expected to expand their service portfolios for non-resident customers. Future developments may include automated investment products, mutual funds, and property management tools designed specifically for overseas participants. Observers note that maintaining compliance with international anti-money laundering standards will remain crucial as these platforms scale their operations across multiple foreign jurisdictions.
Users interested in opening an account can download the mobile application and review the documentation requirements for Pakistan Origin Card, National Identity Card for Overseas Pakistanis, or Computerised National Identity Card holders. Selecting the appropriate category between Non-Resident Account Repatriable and Non-Resident Account Non-Repatriable ensures full alignment with personal financial goals. Monitoring ongoing platform updates will help customers adapt to new features as the digital banking sector evolves.