Microfinance Loans Reach Women Across Pakistan
Women in Pakistan received Rs. 236.2 billion in loans from nonbank microfinance companies during fiscal year 2026, with women accounting for 81.9 percent of their active borrowers, according to a briefing by the Securities and Exchange Commission of Pakistan.
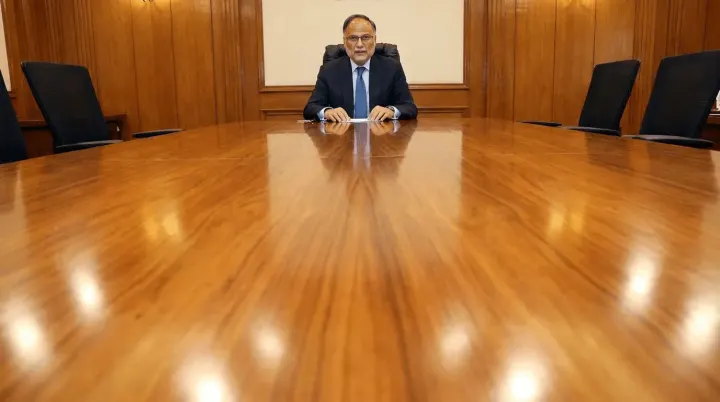
The figures were highlighted during a visit by International Rescue Committee President and Chief Executive David Miliband to the SECP, where he addressed a seminar titled Financial Literacy, Youth and Women's Inclusion.
This massive influx of capital into the hands of female entrepreneurs highlights a shifting dynamic in the national economy, where small loans serve as the primary engine for grassroots commerce. Nonbank microfinance institutions operate differently from traditional commercial banks, relying on group lending models and localized community trust to disburse funds to individuals who lack standard collateral.
Background of Microfinance and Women's Economic Participation in Pakistan
For decades, formal banking institutions in Pakistan remained largely inaccessible to the rural poor and to women without documented property ownership or employment histories. Microfinance emerged as a targeted solution to bridge this gap, providing small amounts of capital to individuals seeking to start home-based enterprises, handicraft production, small retail shops, or livestock farming.
Over the years, policymakers and regulatory bodies recognized that financial inclusion acts as a multiplier for household income and child welfare. When women manage credit and generate independent revenue, studies consistently show that spending on health, nutrition, and education increases correspondingly. The SECP oversees these nonbank microfinance companies to ensure regulatory compliance, consumer protection, and transparent lending rates within the sector.
International Rescue Committee Partnership and Support
Miliband stressed that connecting social development with economic opportunities was essential for achieving sustainable economic independence. Miliband said the International Rescue Committee would work with the SECP to expand women's financial inclusion and support Pakistani women seeking to establish businesses.
He emphasized that providing small business loans to women must go hand in hand with financial education, enabling them to make informed financial decisions and build sustainable businesses. The collaboration between the international humanitarian organization and the national regulator aims to tackle the structural barriers that keep marginalized populations outside the formal monetary system.
Without proper guidance, new borrowers often face difficulties in managing cash flow, pricing goods, or understanding repayment schedules. Integrating literacy programs directly into lending operations helps protect vulnerable borrowers from falling into cyclical debt traps.
SECP Targets 2.5 Million Stock Market Investors
Beyond microloans, regulatory authorities are pushing to broaden participation in formal capital markets. SECP Chairman Dr. Kabir Ahmed Sidhu said a lack of financial awareness remained a major obstacle to public participation in Pakistan's capital markets.
He added that the commission was taking steps to improve access to small business loans for women and had set a target of increasing the number of stock market investors to 2.5 million. Broadening the investor base requires simplifying regulatory procedures, digitalizing account openings, and demystifying stocks and bonds for the average citizen.
Sidhu also said SECP teams were conducting financial awareness activities for young people across the country to encourage greater participation in financial markets and improve financial literacy.
Impact on Local Businesses and Future Outlook
The availability of Rs. 236.2 billion through nonbank lenders directly affects thousands of small commercial ventures run by women who previously relied on informal, high-cost moneylenders. By shifting borrowers into regulated financial channels, the sector provides legal protections and predictable terms of repayment.
Small business owners use these funds to purchase raw materials in bulk, upgrade equipment, or expand distribution networks beyond their immediate neighborhoods. The ongoing educational campaigns conducted by regulatory teams and partner agencies will determine how effectively these businesses scale up over the coming fiscal periods.
Observers will monitor whether the SECP reaches its ambitious investor target of 2.5 million participants and how effectively the new wave of female entrepreneurs translates microloans into long-term commercial viability.